

Marketing 9 min read
UGC for financial services: creator marketing for money transfer brands without compliance risk
UGC for financial services, done safely: diaspora creators, 6 restricted claim areas, disclosure by market and a brief compliance can sign off.
On this page
Quick answer
UGC for financial services is video or photo content made in a creator's own voice to promote a money-handling product. For money transfer brands it works best with diaspora creators who really send money home, a brief with pre-approved claim wording, a clear advertising disclosure for each market, and a logged approval step before any cut runs as an ad.
Key takeaways
- Diaspora creators are believed where stock footage is not, because the sender recognises the occasion, the language and the receive country.
- 6 claim areas need evidence on file before a creator says them: transfer speed, fees, exchange rates, security, savings and guaranteed outcomes.
- Disclosure rules differ by market, so the brief carries a verbatim disclosure line per send country.
- A creator brief with pre-approved wording turns compliance review from a blocker into a checklist.
- One shoot should produce many cuts, and usage rights are agreed before filming, never after.
"Compliance blocks everything we write." Most heads of growth at money transfer operators have said it at least once. Creator content makes it sharper. A creator talks off-script, in their own words, and your compliance approver hears unreviewed fee and speed claims going out under your name.
UGC for financial services does not have to be that fight. The operators who run it well do the compliance work before the camera rolls: claims agreed, disclosure fixed, approver named, rights signed. Then the creator gets freedom inside a fence everyone has already walked.
This guide sets out that method, from choosing diaspora creators to handing over usage rights.
Why diaspora creators work for money transfer brands
A sender choosing a provider for UK to Nigeria is not comparing brand films. They want to know whether someone like them uses it, whether the quoted rate matched what the family received, and whether cash pickup worked first time. A creator who sends money home monthly answers that by being on screen.
Diaspora creators bring 3 things an actor cannot:
- The occasion. School fees in September, Eid, Christmas, the monthly household send, the emergency transfer on a Sunday night.
- The language. Yoruba, Twi, Urdu, Tagalog or Spanish, spoken the way the sender speaks it at home.
- The setting. A screen recording on a mid-range Android phone for an app-led operator, or a real agent counter for an agent-led one.
Stock footage fails the same test every time. Nobody believes it.
What is the difference between UGC content creation and influencer marketing in fintech?
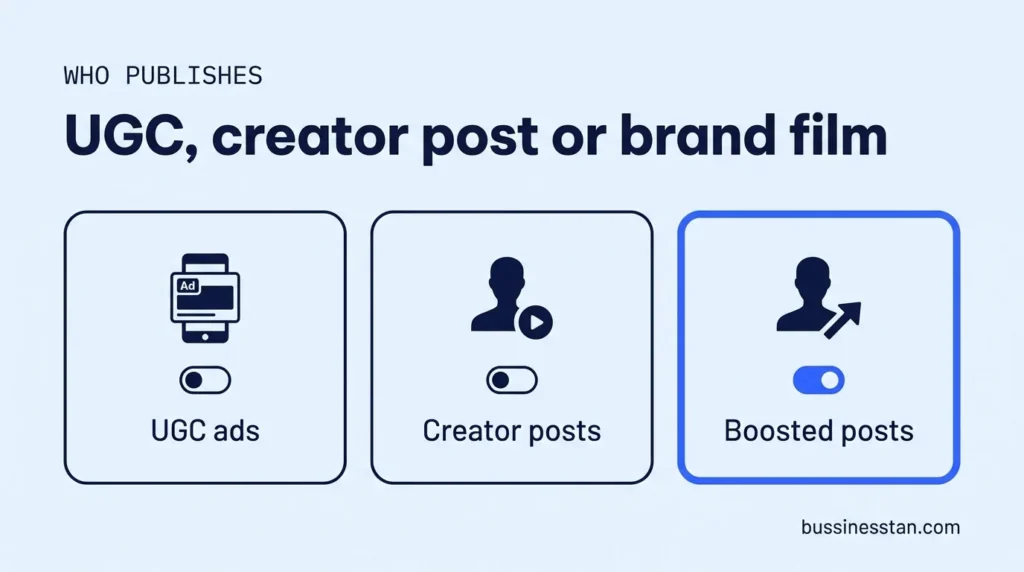
UGC content creation means paying a creator to make content that your brand then runs, usually as paid social ads. Influencer marketing means the creator posts to their own audience. Most "influencer marketing fintech" programmes mix both, and the compliance duties shift with the mix.
| Model | Who publishes | Who controls the edit | Who applies the disclosure | Best use |
|---|---|---|---|---|
| UGC for paid ads | Your ad account | You | You, on every placement | Testing hooks by corridor |
| Creator post (influencer) | The creator | Shared, by contract | The creator, checked by you | Reach inside one diaspora city |
| Creator post boosted as an ad | Both | Shared | Both | Scaling a post that already works |
The 6 restricted claim areas in UGC for financial services
Every creator programme for a money transfer brand holds or fails on 6 subjects. Creators reach for all 6 because senders care about them. Your job is to give them true lines and the evidence behind each.
| Claim area | Risky creator line | Safer approved line | Evidence on file |
|---|---|---|---|
| Transfer speed | "It lands in seconds, every time." | "The app shows the expected arrival time before I pay." | Delivery times by corridor and payout method |
| Fees | "There are no fees." | "I see the fee and the total before I confirm." | Fee schedule by corridor, plus how the FX margin is shown |
| Exchange rates | "Best rate anywhere." | "I check the rate on the quote screen first." | Dated rate comparison, only if any comparison is made |
| Security | "Totally safe, nothing can go wrong." | "I verify with my ID and a selfie when I sign up." | Description of the actual controls, signed off by your security owner |
| Savings | "I save £20 every time." | "I compare what my family actually receives." | Calculation method, date and corridor for any figure |
| Guaranteed outcomes | "Guaranteed to arrive." | "I can track the transfer in the app." | The tracking feature, as it exists today |
The "no fees" line deserves its own warning. A zero-fee claim on a product that earns through the FX spread is the classic complaint, and it is exactly the line a creator will improvise. Put it on the banned list in writing.
Licensing and AML questions go to a qualified adviser. We handle advertising and marketing compliance.
Disclosure: what the rules ask for, by market
Disclosure rules differ by send country, and they change. Treat the table below as a starting point your adviser confirms, not a legal opinion.
| Market | Source | What it asks for, in short | What goes in the brief |
|---|---|---|---|
| UK | ASA and CAP Code guidance on recognising ads on social media | Ads must be obviously identifiable. The ASA expects a prominent "Ad" label upfront and advises against labels such as "sponsored", "gifted" or "spon". | "Ad" at the start, on screen and in the caption |
| UK, financial promotions | FCA finalised guidance FG24/1 (March 2024) on financial promotions on social media | Promotions must be fair, clear and not misleading, including content by influencers. Whether it applies to your promotions depends on your permissions. | A line for your compliance adviser to confirm or strike |
| US | FTC, "Disclosures 101 for Social Media Influencers" | Disclose material connections, place the disclosure in the content itself rather than only in a profile or description, repeat it during live streams, and do not rely on a platform tool alone. | Spoken and on-screen disclosure, plus the platform tool |
| Gulf and other send markets | Local media and advertising rules | Requirements vary and are updated often. | A per-market line agreed with your local adviser before filming |
The practical rule that satisfies most markets: a verbatim disclosure at the start of the video, both spoken and on screen, with the platform's paid-partnership label added on top.
Creator brief compliance: write the claims before the script
Creator brief compliance is decided before a creator is booked. If the claims list does not exist yet, write it first. Scripts written without one come back from review with red lines on every page.
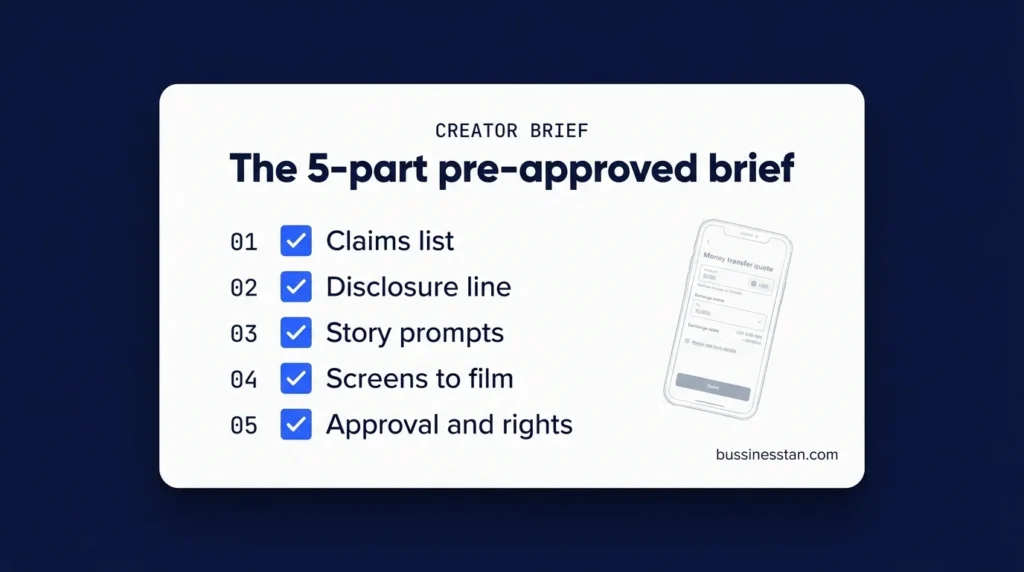
The 5-part pre-approved creator brief
- Claims list. Approved lines, word for word, and the banned lines next to them. Each approved line points to its evidence.
- Disclosure line. The verbatim sentence for each market the ad will run in, and where it appears.
- Story prompts. 3 to 5 real sending occasions (school fees, an emergency, the monthly household send), so creators tell their own version instead of reading yours.
- Show, don't claim. Screens to film: the quote screen, the fee line, the tracking screen. Filmed on a test account, so no real sender, beneficiary or document data appears.
- Approval and rights. The named approver, the turnaround time, the usage term, territories and whether the content can run from the creator's handle.
This is the work our UGC content creation team does: creators sourced per receive country, scripts checked against the claims list, and nothing filmed until the brief is signed.
One shoot, many cuts, and an approvals workflow that holds
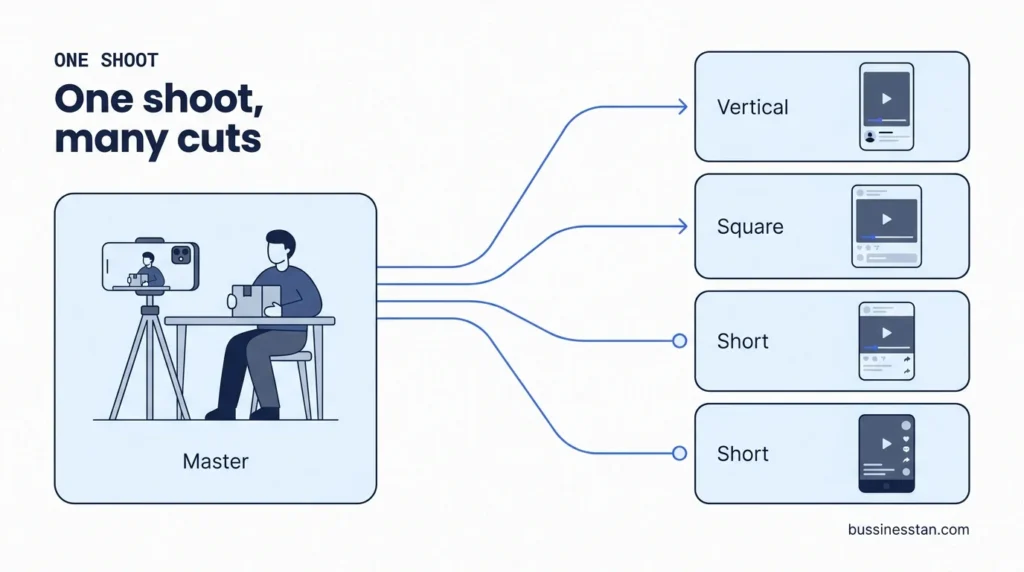
One filming session should feed a month of testing: vertical, square and short versions, each with a different opening hook. Paid media decides which hooks earn a first transfer.
| Step | Owner | Output |
|---|---|---|
| 1. Brief signed | Marketing lead and compliance approver | Claims list and disclosure lines locked |
| 2. Creators shortlisted | Marketing | 3 to 5 creators per corridor |
| 3. Scripts checked | Marketing, then compliance | Every claim traced to the list |
| 4. Filming | Creator | Master footage plus app screen recordings |
| 5. Rough cut review | Compliance | Voice and on-screen text checked together |
| 6. Final approval logged | Named approver | Dated record of what was approved |
| 7. Launch and read | Paid media | Cost per first send by creator and hook |
If approvals already stall across paid, CRM and social, the fix is the path itself. That is what marketing operations optimisation covers: one campaign route with compliance placed before the build, not after it.
Judge the cuts on first transfers, not views. Creator ads on TikTok and Meta collect cheap views from outside the corridor. A view is not a sender. Paid creator ads also need a verified advertiser account; our note on financial services ad verification covers that path.
Usage rights: agree them before anyone films
Rights disputes surface at the worst moment, usually when a cut is finally working. Agree these points in the creator contract:
- Term. How long you can run the content, and what happens when it ends.
- Territories and channels. Organic, paid, and whether the ad can run from the creator's own handle.
- Edits. Your right to cut, caption, translate and add disclosure.
- Category exclusivity. Whether the creator can film for another money transfer brand in the same period.
- Takedown. Your right to pull a cut when a fee, rate display or payout option changes and the claim is no longer true.
- Data. No real sender, beneficiary or document data on screen, ever.
Fees change. A cut that was accurate in March can mislead by June.
Creator cuts can also support repeat sends before known sending dates, which fits our guide to earning the second transfer.
Frequently asked questions
Is UGC for financial services allowed in the UK?
Yes, if the content is identifiable as advertising and every claim is accurate and evidenced. The ASA expects a clear "Ad" label upfront on influencer content, and FCA social media guidance may also apply depending on your permissions. Confirm your position with your compliance adviser before booking a creator.
What should a creator brief for a money transfer app include?
Five parts: an approved claims list with banned lines, a verbatim disclosure line per market, 3 to 5 real sending stories, the app screens to film on a test account, and the approval and rights terms. Creator brief compliance is settled when this document is signed, before any script is written.
Do diaspora creators need to be real senders?
For testimonial-style content, yes. A creator who describes sending money home should actually do it, with your product, on that corridor. Where that is not true, film a demo or explainer instead and keep first-person transfer claims out.
How do you measure UGC content creation for a remittance app?
Tag every cut by creator, hook and corridor, then read cost per verified sender and cost per first send for each tag. Views help early, but they do not pay. Rebook the creators whose cuts produce first transfers at an acceptable cost.
Who is responsible for the ad disclosure, the brand or the creator?
Both, in practice. On paid ads from your account, you apply the label on every placement. On posts from the creator's handle, the creator adds it and you check it before and after publishing. The FTC also warns against relying only on a platform's disclosure tool, so put the wording in the contract.
Where to start
Start with the claims list, not the creators. Write the 6 restricted areas down, attach the evidence you actually hold, and agree the disclosure line for each send market. Then brief 3 creators, not 30, and let first transfers decide who stays.
If you want an outside read of how your creative, claims and paid media fit together, Book a Growth Audit. It takes 14 days, costs a fixed fee, and you keep the roadmap whether or not we work together.
Written by
Founder & CEO, Bussinesstan
Owns the commercial side of every engagement: fixed-fee scoping, corridor economics, and the reporting that ties spend to completed first transfers rather than to installs.
Meet the team
Activation emails for remittance apps: a sequence for senders who verified and never sent
Activation emails for remittance apps: a 6-message trigger sequence, subject line patterns, channel rules and measurement on funded first transfers.
Fintech customer retention for remittance apps: earning the second transfer
Fintech customer retention for remittance apps: lifecycle stages, 3 retention levers, corridor-based dormancy and reactivation without discount habits.
Fintech marketing strategy for remittance companies: the 2026 playbook
A fintech marketing strategy for remittance companies built on first transfer, send frequency and corridor mix, with a channel map and 90-day plan.